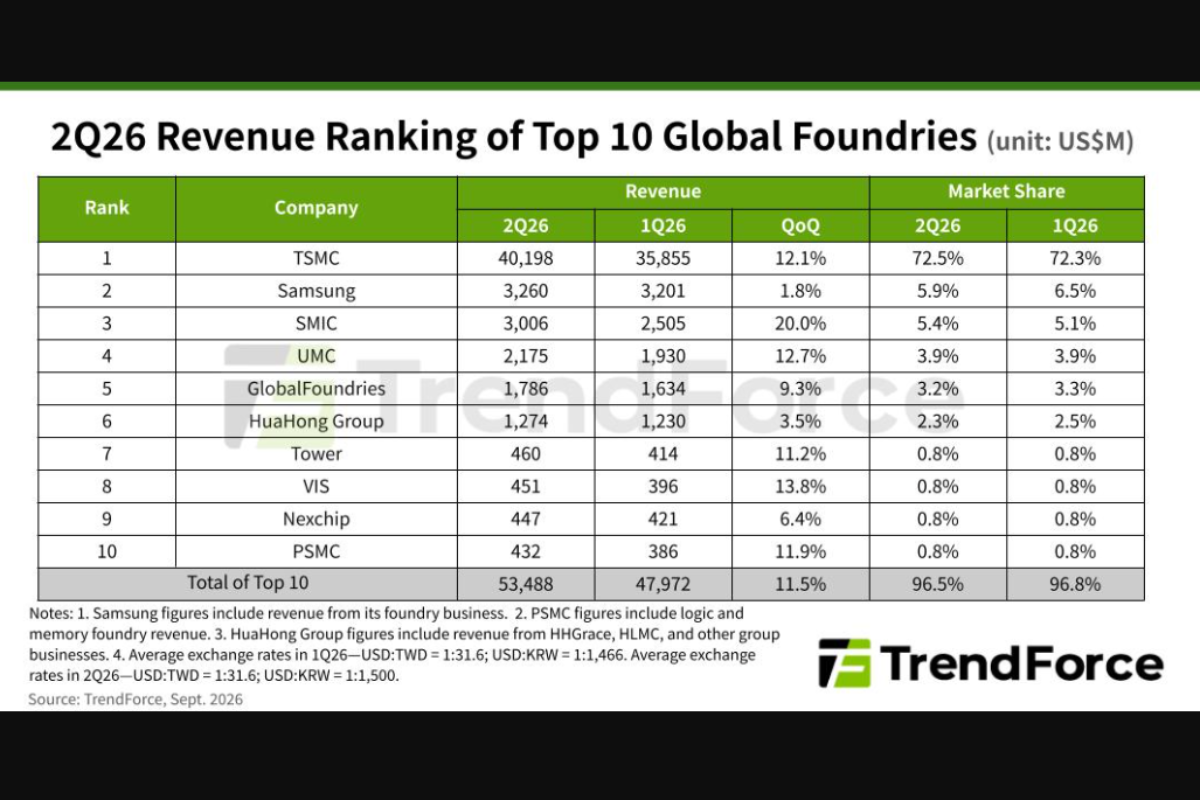
TrendForce's latest foundry industry research shows the combined revenue of the world's top 10 foundries rose 11.5% quarter-over-quarter to nearly $53.49 billion in the second quarter of 2026, setting another record high. Growth was driven by ongoing capacity constraints for advanced manufacturing processes used in AI and high-performance computing (HPC) chips, along with rising demand for peripheral AI components like power management ICs (PMICs) and discrete power components. Continued advance stockpiling across consumer electronics supply chains, including TVs, PCs, and laptops, also tightened available capacity for some older manufacturing processes.
Looking ahead to the third quarter, consumer chip design customers are expected to keep wafer production steady amid concerns that capacity for mature manufacturing processes could remain tight and wafer prices may keep rising. The seasonal ramp-up of flagship smartphone production and growing output of next-generation AI and HPC platforms are also expected to further lift foundry revenue.
Among the top 10 foundries, TSMC kept its lead, with second-quarter revenue nearing $40.2 billion, up 12.1% quarter-over-quarter, giving it a 72.5% market share. Strong demand for AI server GPUs and custom processors (XPUs) kept its 5nm/4nm and 3nm production capacity fully booked. Early inventory buildup ahead of new iPhone launches also supported sales, and TSMC's 2nm process contributed revenue for the first time. Together, these factors drove growth in both the number of wafers shipped and average selling prices.
Samsung Foundry ranked second. New orders for advanced processes, including base dies used in high-bandwidth memory, gradually ramped up during the quarter, while pricing for its 5nm/4nm and more advanced processes increased. Revenue rose slightly, up 1.8% quarter-over-quarter to $3.26 billion, though Samsung's market share declined to 5.9% as competitors grew faster.
SMIC ranked third, with revenue surging 20% quarter-over-quarter to more than $3 billion. Its market share edged up to 5.4%, narrowing the gap with Samsung. Growth was supported by advance stockpiling across consumer supply chains, particularly PCs and laptops, along with steadily increasing orders for AI peripheral chips and server networking products. Widespread memory shortages also drove stronger demand and pricing for NAND and NOR flash memory manufactured through foundry services.
UMC held onto fourth place with a 3.9% market share. The company benefited from advance procurement of PCs, laptops, and certain consumer electronics earlier in the year, along with increased orders for server-related products like FPGAs. A significant recovery in utilization of its older 8-inch wafer capacity also helped. As a result, second-quarter revenue rose 12.7% quarter-over-quarter to nearly $2.18 billion.
GlobalFoundries ranked fifth, supported by renewed orders from consumer customers and growing demand for AI and server peripheral components, including power ICs and transimpedance amplifiers/drivers used in optical communications. Both wafer shipments and average selling prices increased during the quarter, lifting revenue 9.3% quarter-over-quarter to approximately $1.79 billion, with market share at 3.2%.
HuaHong Group ranked sixth, with second-quarter revenue rising 3.5% quarter-over-quarter to more than $1.27 billion. Stable orders for NOR flash memory and AI-related PMICs supported growth, while earlier wafer price increases began contributing more meaningfully to revenue and average selling prices. Gradual capacity ramp-up at subsidiary HHGrace also supported the group's growth.
Tower took seventh place with revenue of $460 million, up 11.2% quarter-over-quarter. Growth was driven by higher shipments and production of chips used in AI optical transceiver modules, including transimpedance amplifiers/drivers and photonic ICs.
VIS moved back into eighth place as advance procurement and rising orders for AI peripheral chips and smartphone PMIC and power products boosted wafer shipments and pricing. Revenue increased 13.8% quarter-over-quarter to $451 million.
Nexchip slipped to ninth place despite a 6.4% quarter-over-quarter revenue increase to $447 million. Orders for its core display driver IC products returned as other foundries increasingly allocated capacity elsewhere, and advance procurement of consumer products also boosted capacity utilization and shipments. However, its growth remained weaker than that of AI-related power products from competitors, resulting in a decline in ranking.
PSMC ranked tenth, with revenue rising 11.9% quarter-over-quarter to $432 million. Although overall shipment volumes increased only modestly, deliveries of memory and logic wafers reflecting earlier price increases helped drive the revenue growth.