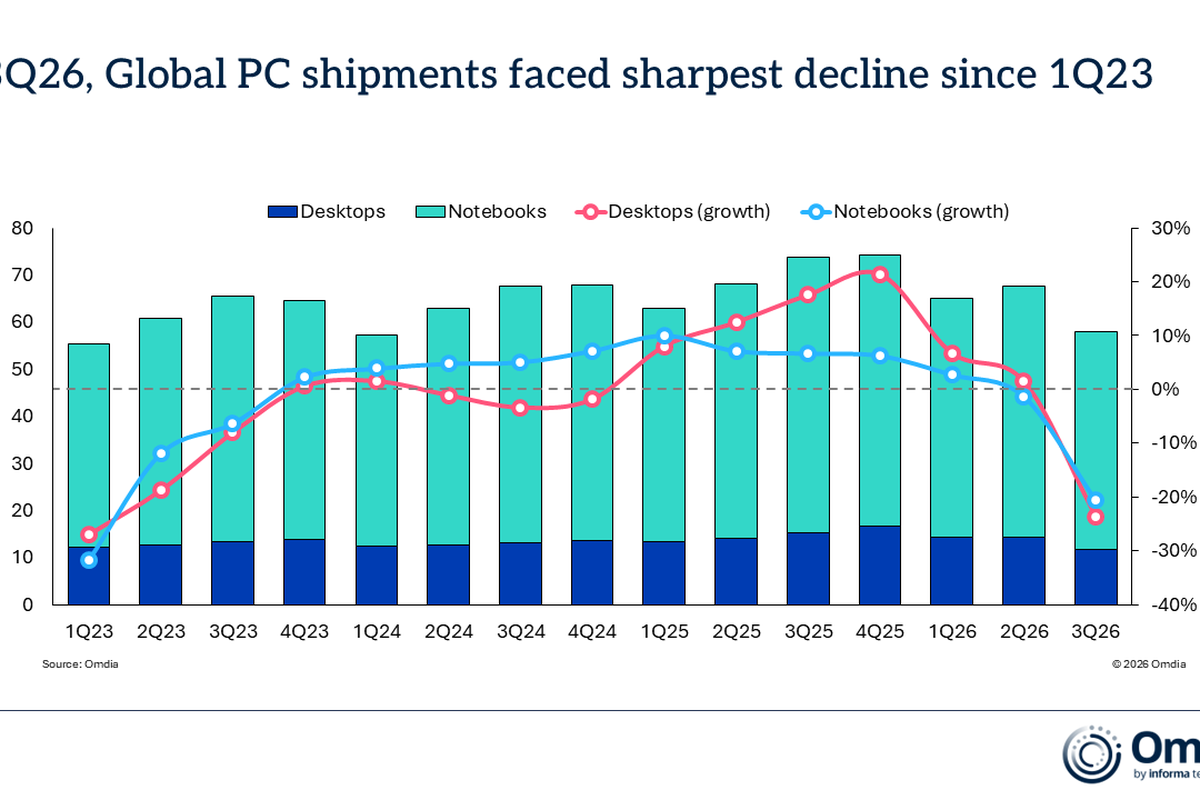
Omdia reported worldwide shipments of desktops, notebooks and workstations fell 21.2% year on year to 58.1 million units in 3Q26. Desktop shipments, including desktop workstations, fell 23.5% to 11.7 million units, while notebook shipments, including mobile workstations, declined 20.6% to 46.4 million units.
Ishan Dutt, research director at Omdia, said the drop followed sustained pull-forward activity in the first half of the year. He said upstream component cost increases had worked through to end-market prices, while vendors and their ODM partners scaled back production and channel partners continued to work through elevated inventory levels.
Omdia said supply chain challenges had intensified, with rising memory and storage prices and shortages of processors, graphics cards and numerous IC components making supply and inventory management more difficult for PC vendors. Ben Yeh, principal analyst at Omdia, said: “The cost share of DRAM and SSDs in PCs has risen sharply from a typical level of around 15% to nearly 40%, with price increases more than fourfold.”
Omdia forecasts the PC market will decline 24% year on year in 4Q26, followed by a further 7% decline for full-year 2027.
The rankings of the leading vendors remained largely unchanged sequentially and year on year. Lenovo retained the top position with 14.9 million units shipped and 26% market share. HP ranked second with 10.3 million units, down 31%, and an 18% share, nearly three percentage points below a year earlier. Dell shipped 7.6 million units for a 13% share, while Apple ranked fourth with 6.8 million units, down 11% year on year. Asus rounded out the top five with 5.4 million units; its market share improved to 9.3% year on year.